
Oxera Repair Products
Securing recovery cash when flood defences are exceeded

Climate and nature-related risk: Flood damage and a cash-flow shortfall while insurance claims are assessed and paid
Solution pathway: Physical flood protection; pre-agreed insurance trigger; rapid access to recovery funds
Business type: SME manufacturing business
Sector: Construction repair products
Geography: Mirfield, West Yorkshire, United Kingdom
In practice
Flooding can create a financial emergency even where a business has insurance. The UK Green Building Council’s case studydescribes how Oxera waited more than seven months for a claim following flooding in 2015. Cash reserves allowed operations to continue, but the delay exposed the importance of payment timing.
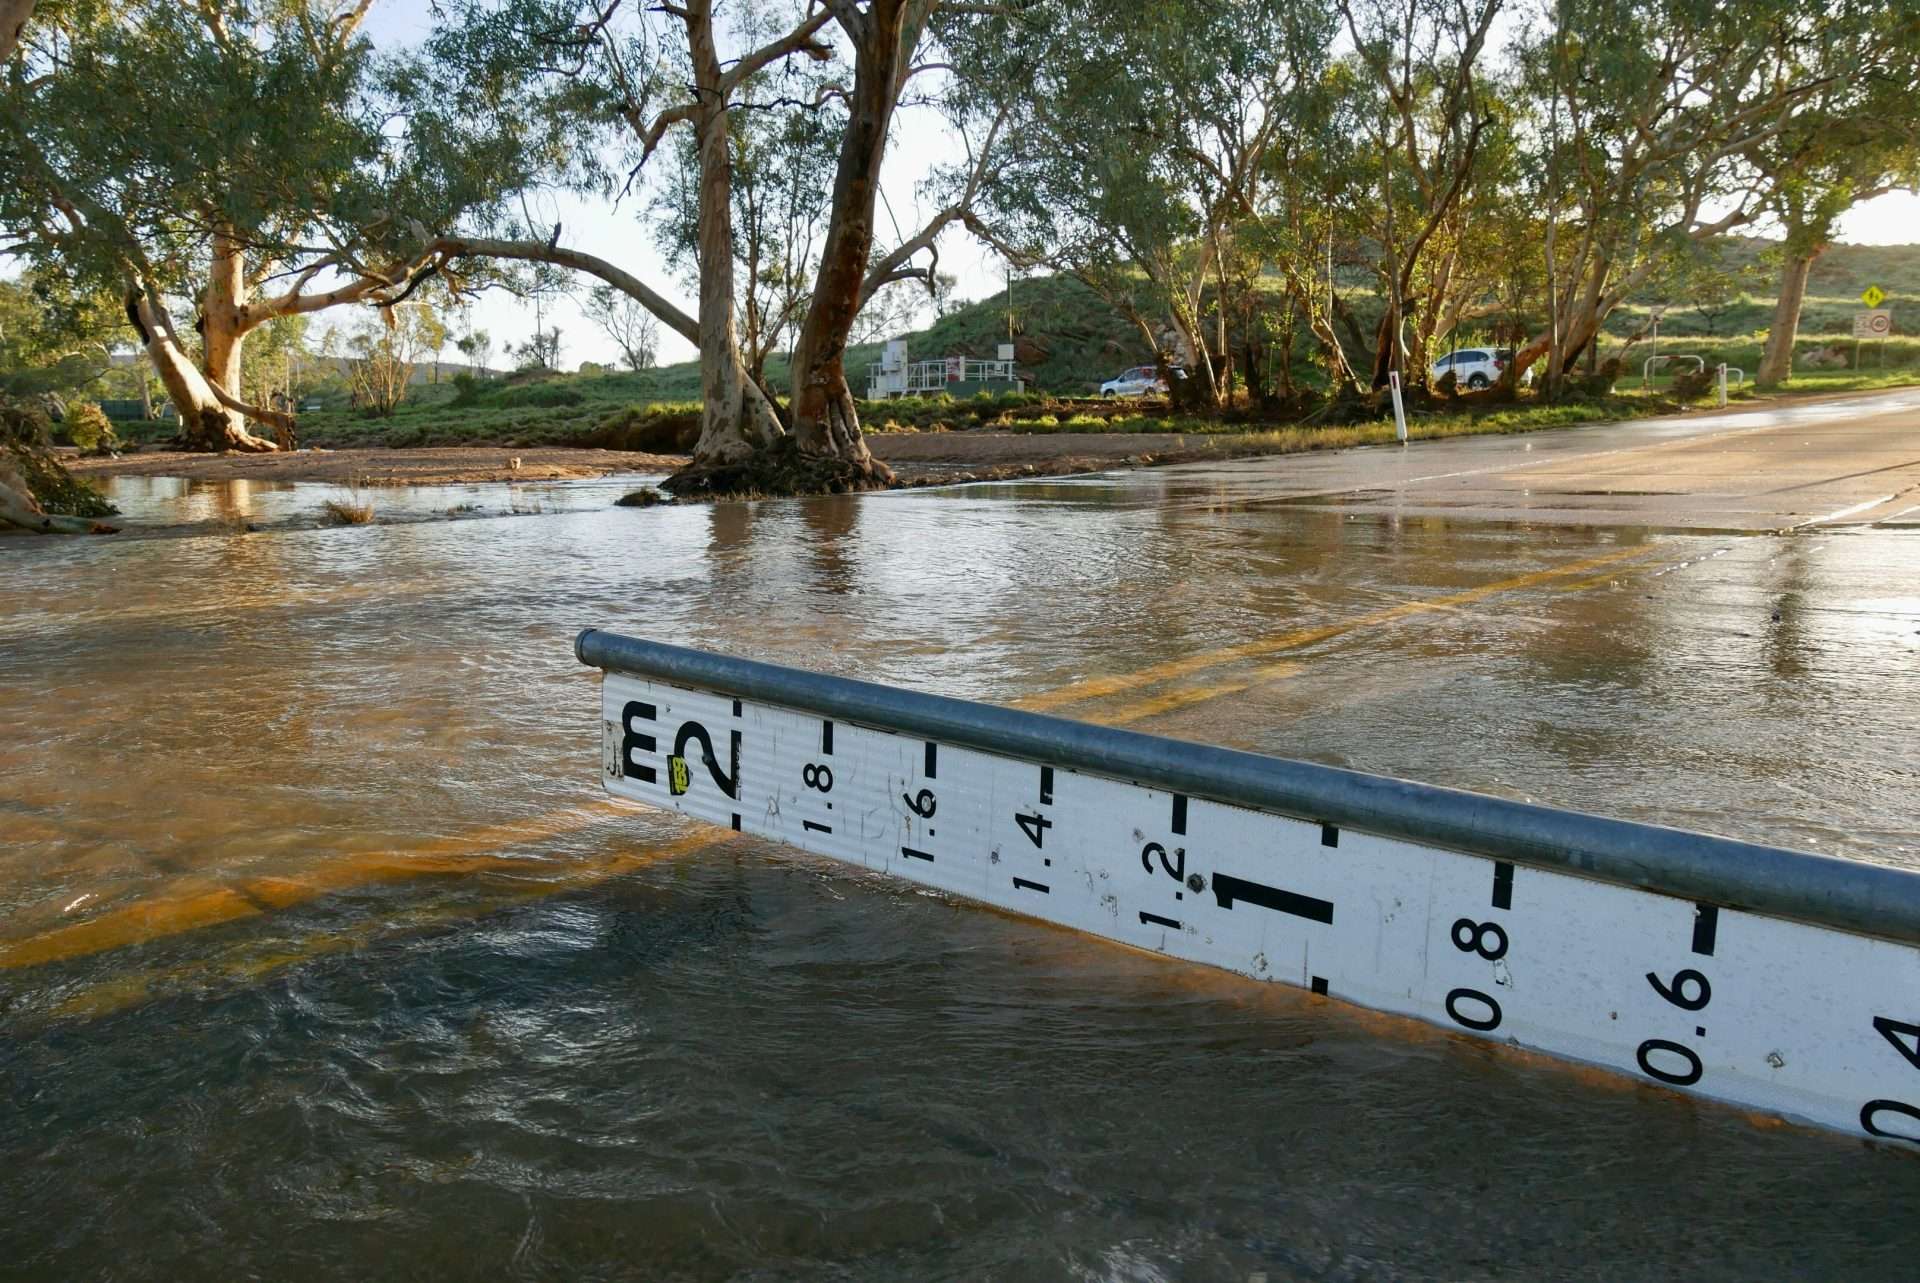
Oxera subsequently purchased FloodFlash insurance alongside its flood gates. The company selected a water-depth trigger in relation to those defences: when a sensor recorded the agreed depth, the policy would activate a pre-agreed payment. When Storm Ciara breached the gates in 2020, Oxera received its payout in less than 24 hours.
Parametric insurance works differently from conventional indemnity insurance. Once the agreed water depth was verified, FloodFlash paid the amount set in advance. With parametric insurance, the payout is not calculated from proof of the full amount of actual loss. This can provide recovery cash quickly, but the payment may be higher or lower than the costs Oxera ultimately incurs.
Parametric insurance works differently from conventional indemnity insurance. Once the agreed water depth was verified, FloodFlash paid the amount set in advance. With parametric insurance, the payout is not calculated from proof of the full amount of actual loss. This can provide recovery cash quickly, but the payment may be higher or lower than the costs Oxera ultimately incurs.
Latest News
The approach combines investment in damage prevention with planning for the money needed when protection is exceeded. Because payment depends on the agreed trigger, the amount received may differ from actual losses. Businesses therefore need to consider how trigger depth, payout size and existing reserves fit their recovery needs.
Why this example was selected
The example is featured in UKGBC’s solutions library, providing sector-platform visibility beyond the insurer’s website. It shows a clear connection between physical protection, insurance design and payment speed during a real flood. UKGBC identifies the information as a member contribution rather than a commercial endorsement, so the reported outcome should be understood as a documented customer example rather than an independent evaluation.
Key lesson
Plan for recovery cash flow alongside asset protection. Assess how insurance triggers, payment amounts and timing correspond to likely disruption, and retain a plan for losses that exceed or fall outside cover.
